Eligibility for both
Your property, existing solar, household income bracket and the battery size, checked against the current rules for the discount and the loan at the site visit.
Federal battery discount · NSW zero-interest loan
The federal Cheaper Home Batteries discount comes off the price on the day. The NSW Home Energy Saver loan can cover what is left at 0% interest. We work out both at the assessment.
How the two fit together
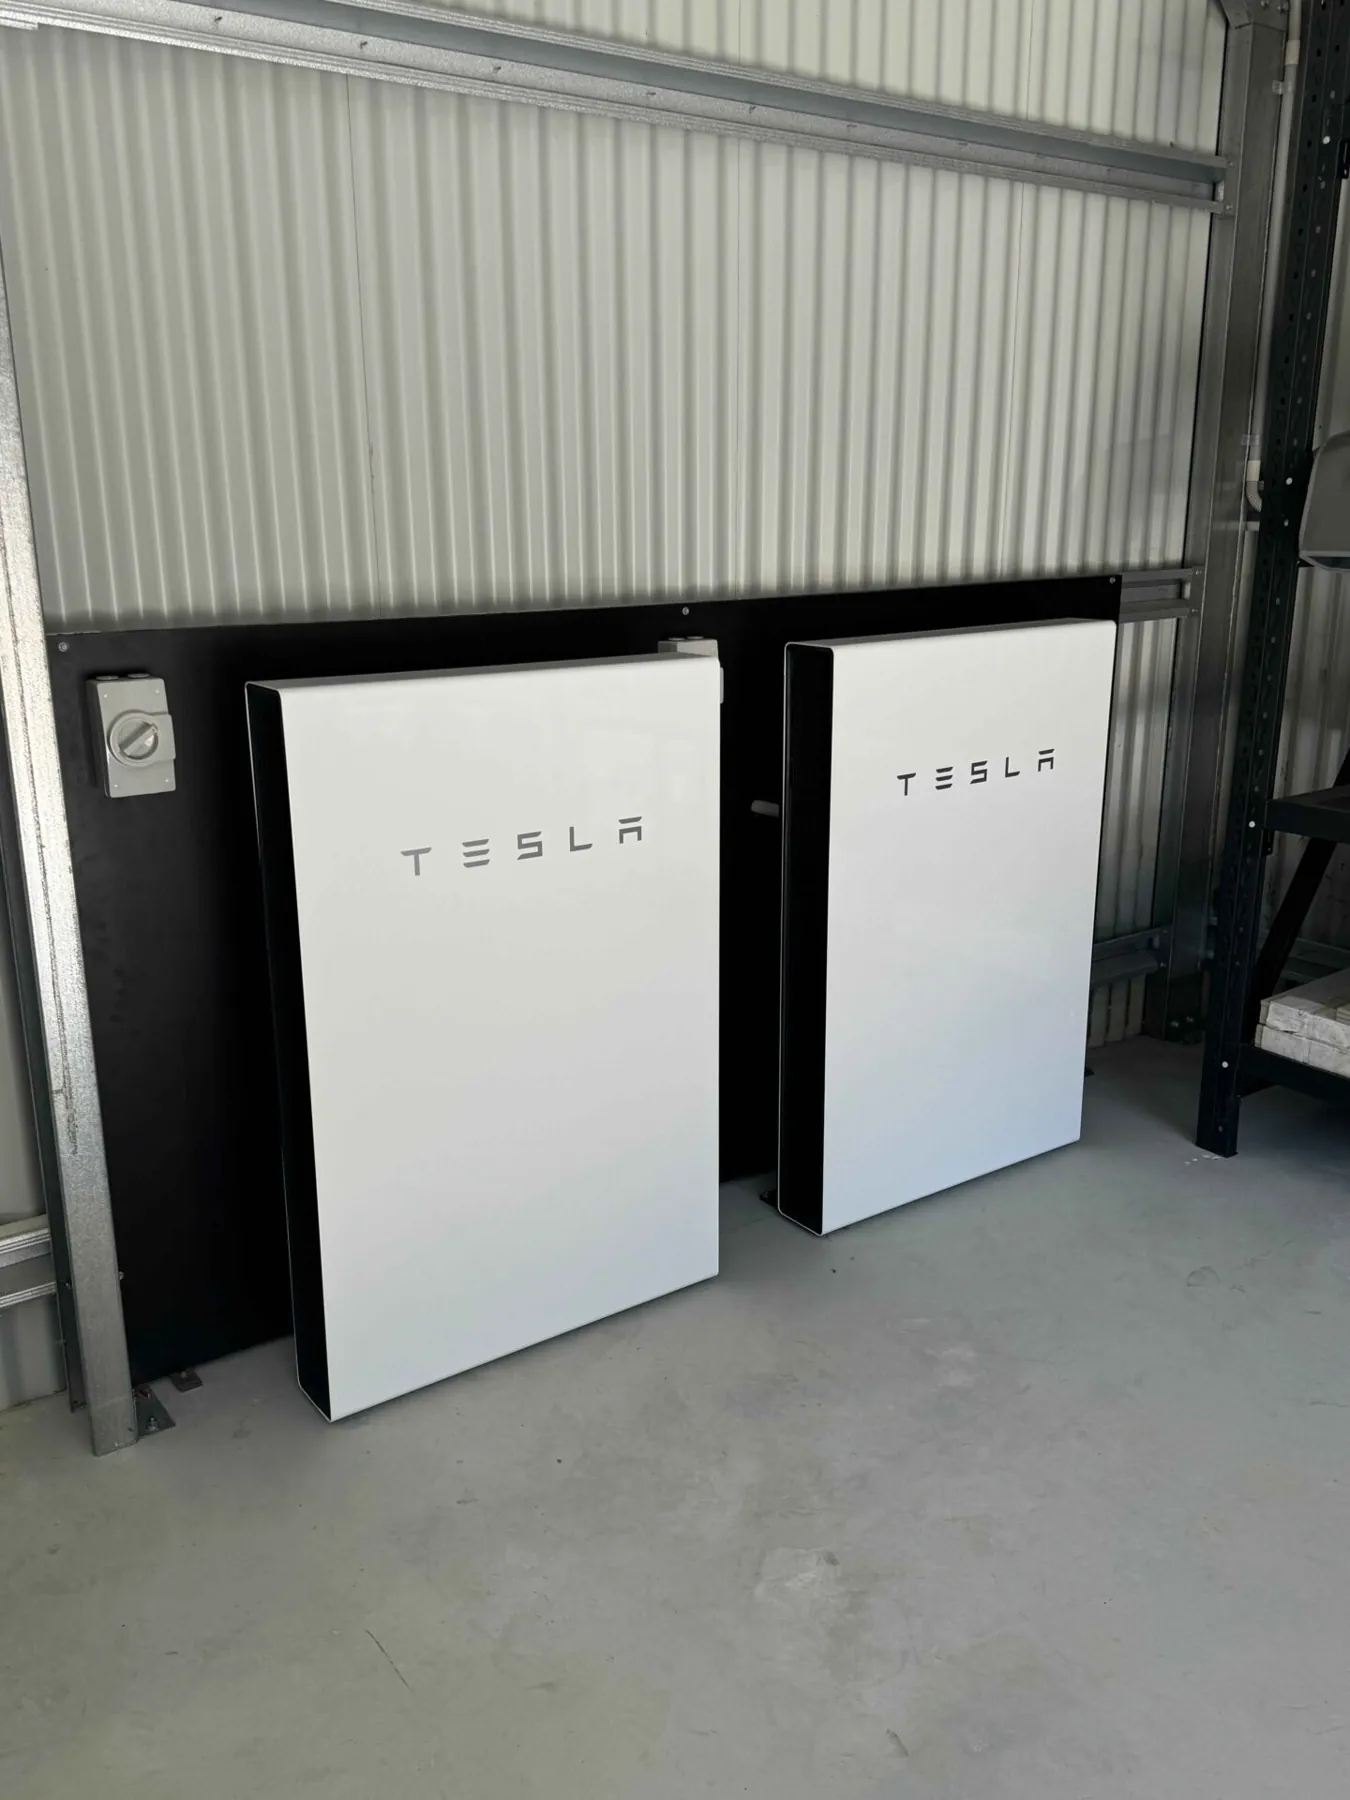
There are two government programs that matter if you are putting a battery in this year. The first is the federal Cheaper Home Batteries Program, a discount on the battery itself that we apply as your accredited installer, so it comes straight off the quote. The second is the NSW Government Home Energy Saver loan, which lends eligible households up to $15,000 at zero interest to pay for what is left.
They work in that order. The discount brings the price down, and the loan spreads the balance over up to ten years with no interest and no establishment or account-keeping fees. Between the two, a battery can go in with little or nothing paid up front, depending on the size of the system.
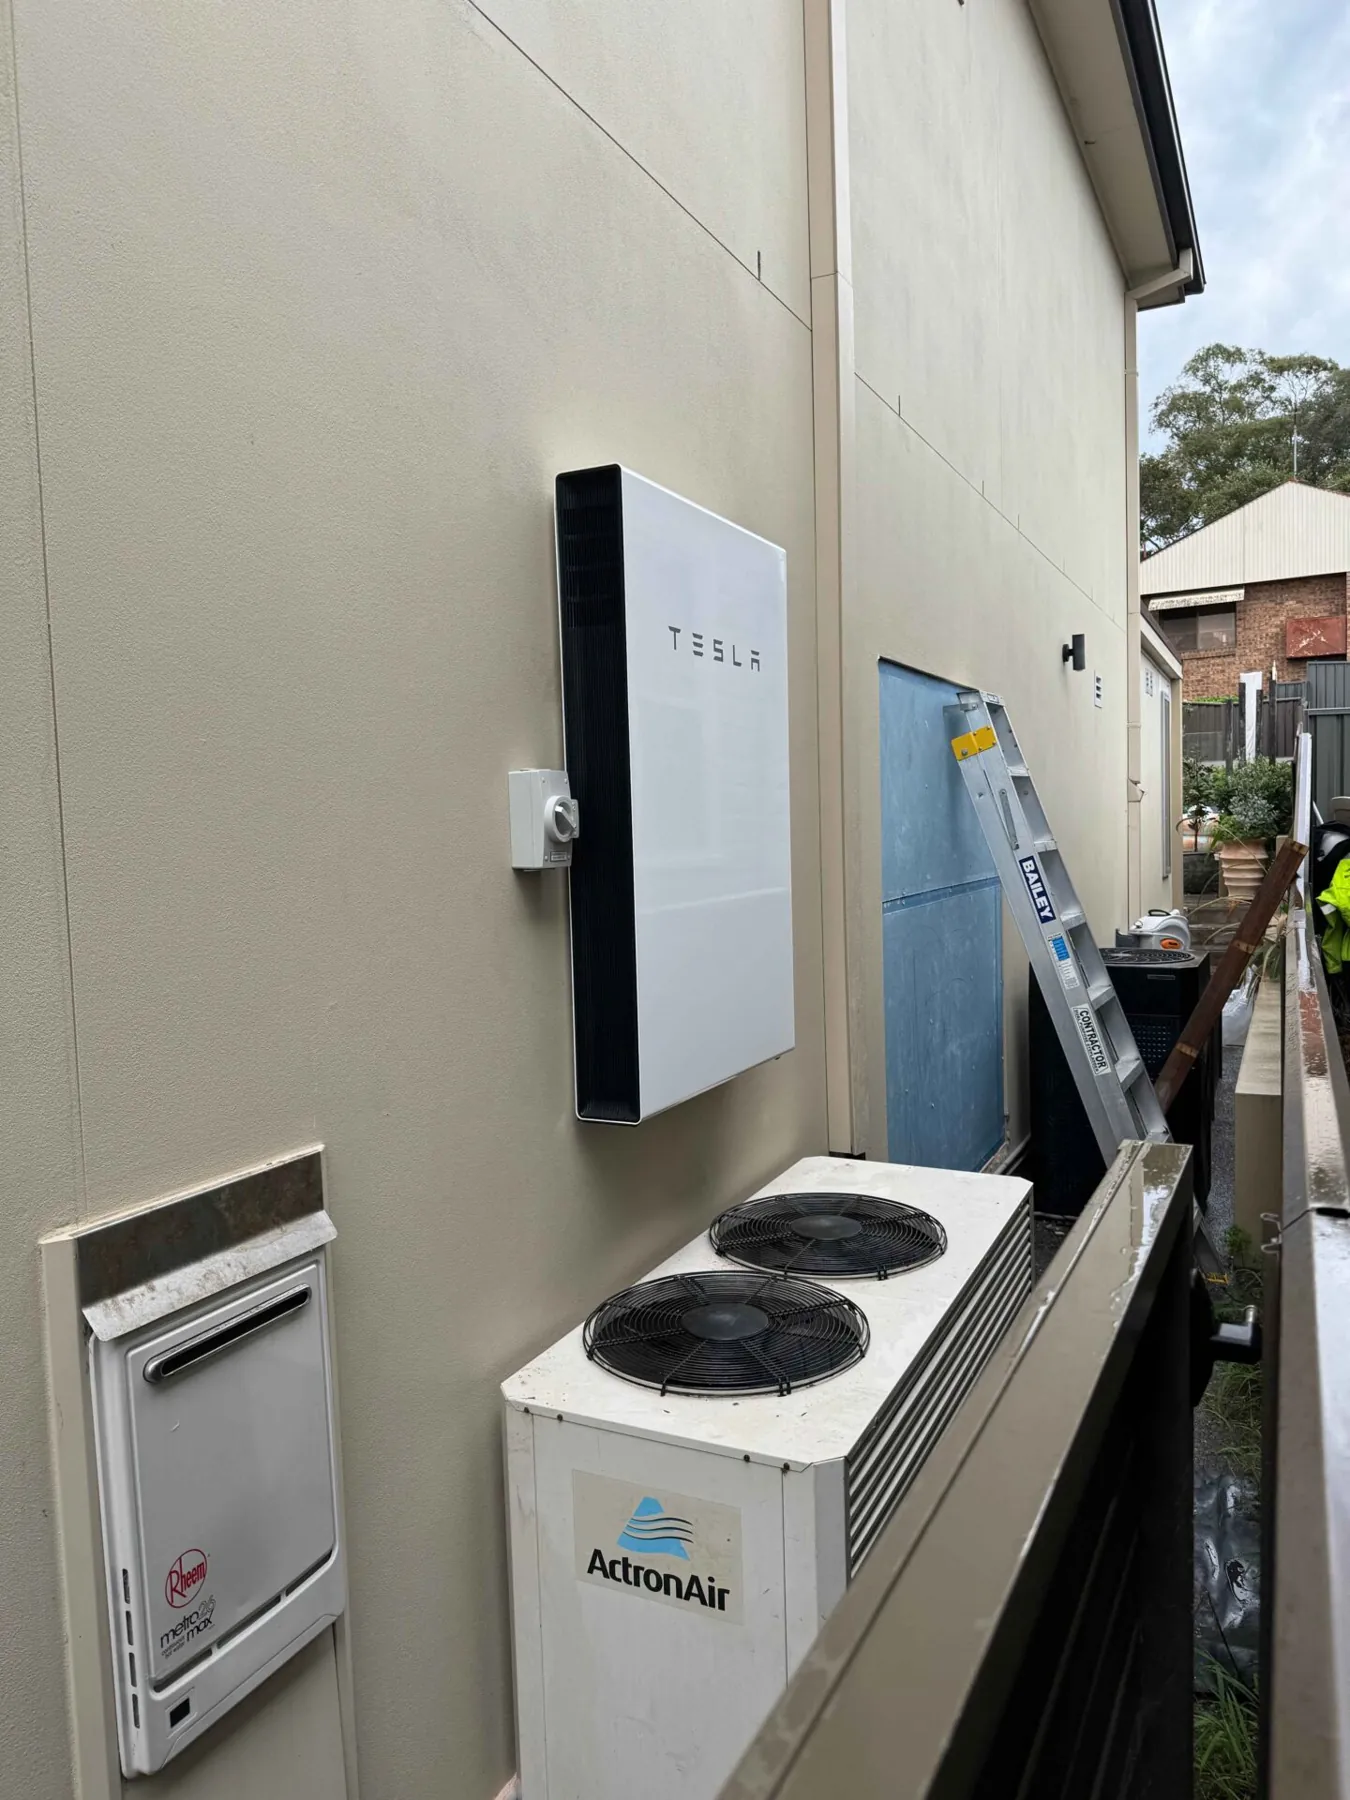
The federal program has run since 1 July 2025. When an accredited installer puts in an eligible battery, the program creates certificates for it, and the value of those certificates comes off your price. It is not a rebate you claim back later and it is not means-tested.
The rate is set by the day the battery is installed, not the day you sign. It dropped on 1 May 2026, drops again on 1 January 2027, and then steps down every six months until the program ends in 2030. Since May the full rate applies to the first 14 kWh of usable capacity, with less on anything above that, which happens to suit the size most homes need.
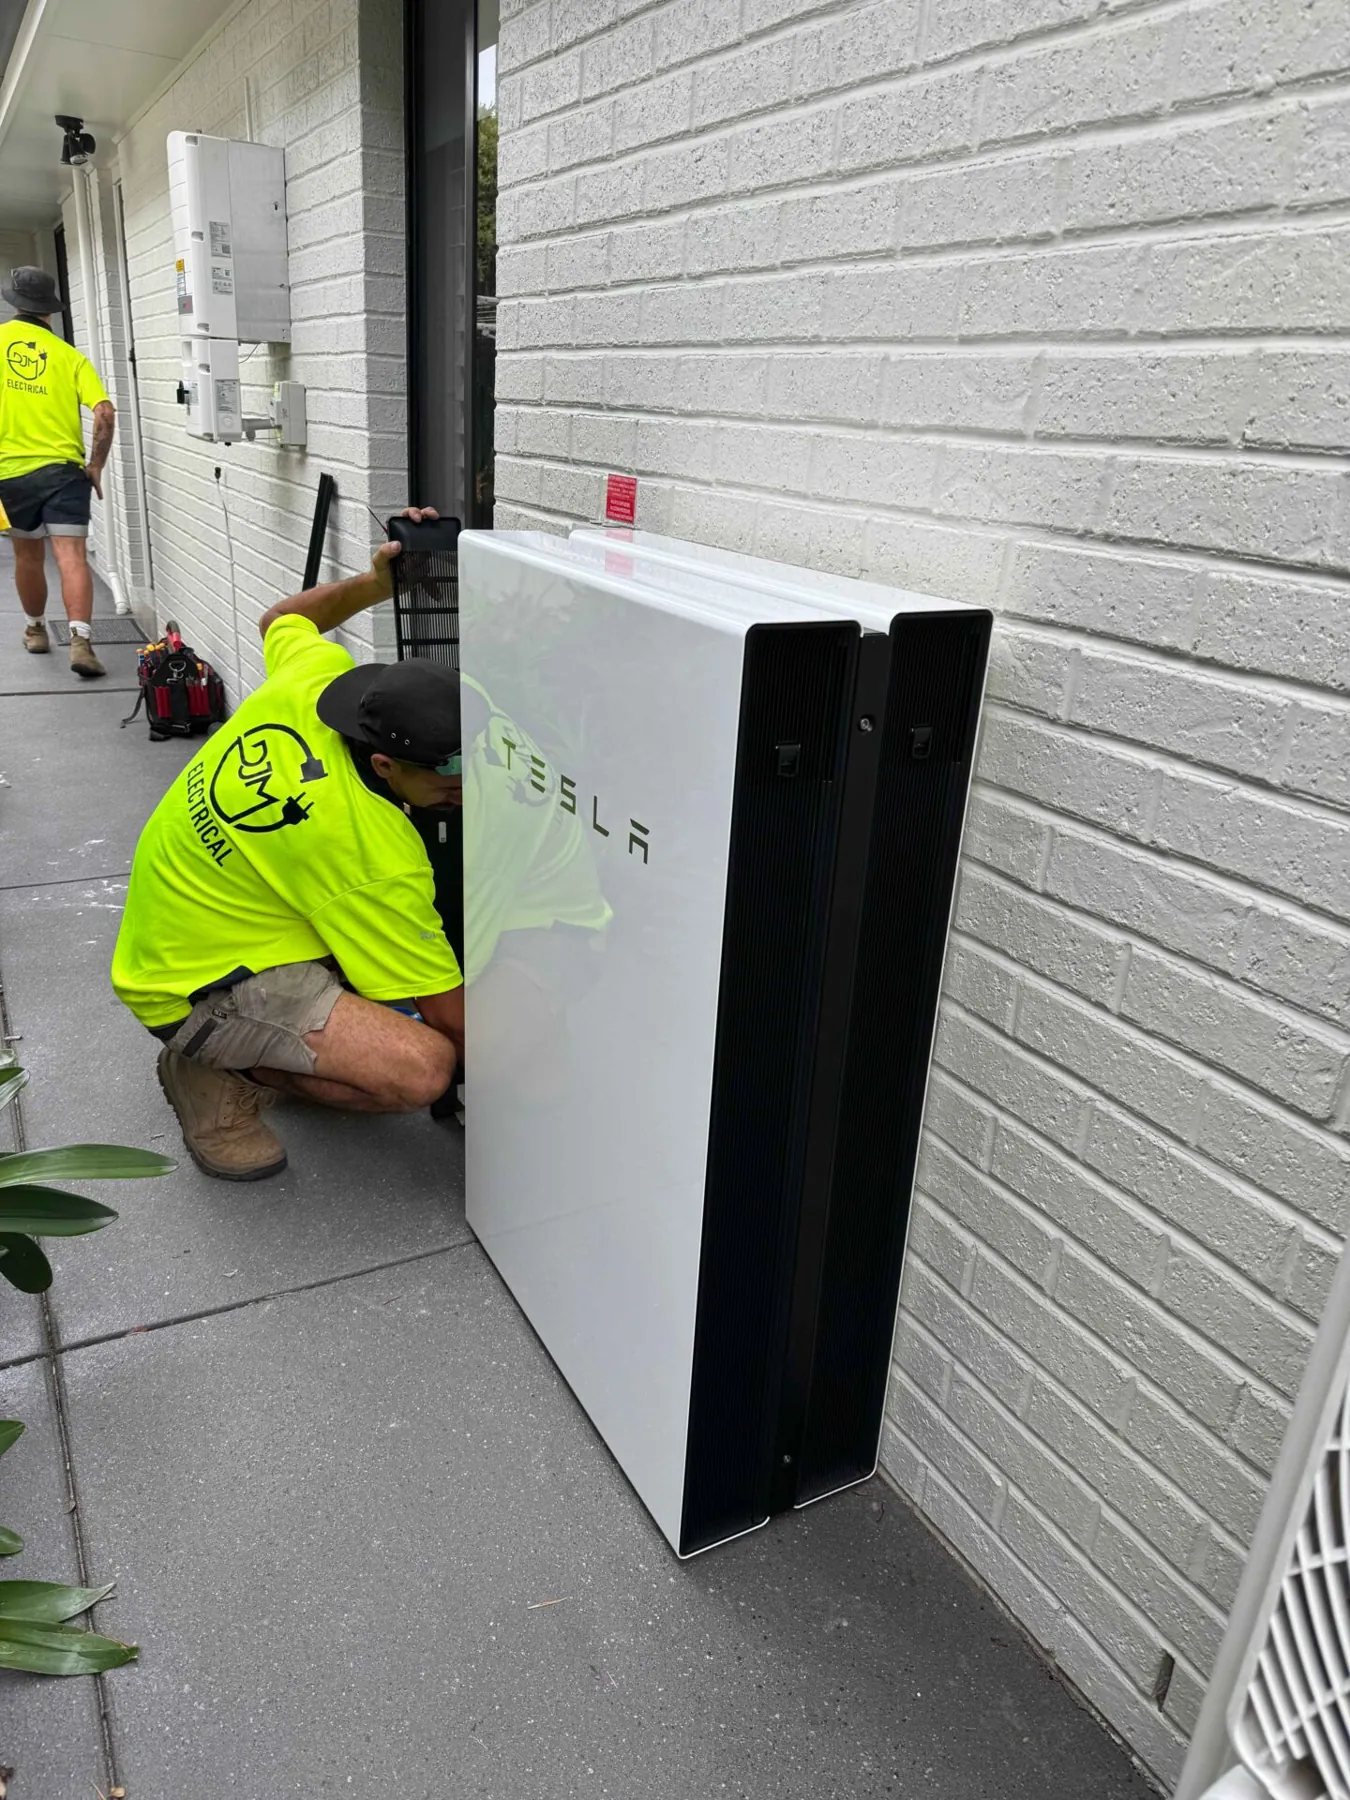
The NSW Government opened its Home Energy Saver loans on 17 June 2026. Eligible households can borrow up to $15,000 at 0% interest, repaid over up to ten years, for a home battery and other upgrades. The loans are delivered for the Government by Brighte and Plenti, and the same loan can also cover rooftop solar or a switchboard upgrade, within the $15,000 limit.
To qualify you need to own the property in NSW, as the homeowner or the landlord, with a combined household taxable income of $210,000 or less, and pass the lender's credit check. The battery has to be paired with solar, internet connected, able to join a virtual power plant and carry a 10-year warranty. We only quote batteries that meet the rules for both programs.
The loan at a glance
The federal discount moves every six months. The loan terms are set by the NSW Government, so these we can print.
The federal battery discount drops again on 1 January 2027, then every six months after that.
Get your numberWhat we handle
Your property, existing solar, household income bracket and the battery size, checked against the current rules for the discount and the loan at the site visit.
Approved product list, virtual power plant ready, 10-year warranty, paired with solar. If a battery would miss out on either program, we do not quote it.
The federal discount appears as a line item on your itemised quote, so the figure you take to the lender is the real one.
We show you exactly what is left after the discount, so you know what to apply for and whether solar or a switchboard upgrade fits under the same $15,000.
Certificates, declarations and network paperwork lodged by us. One customer waited for the rebate to be confirmed before committing and was never chased once.
Monitoring set up on your phone, and the same crew on the end of the line afterwards.
How it runs
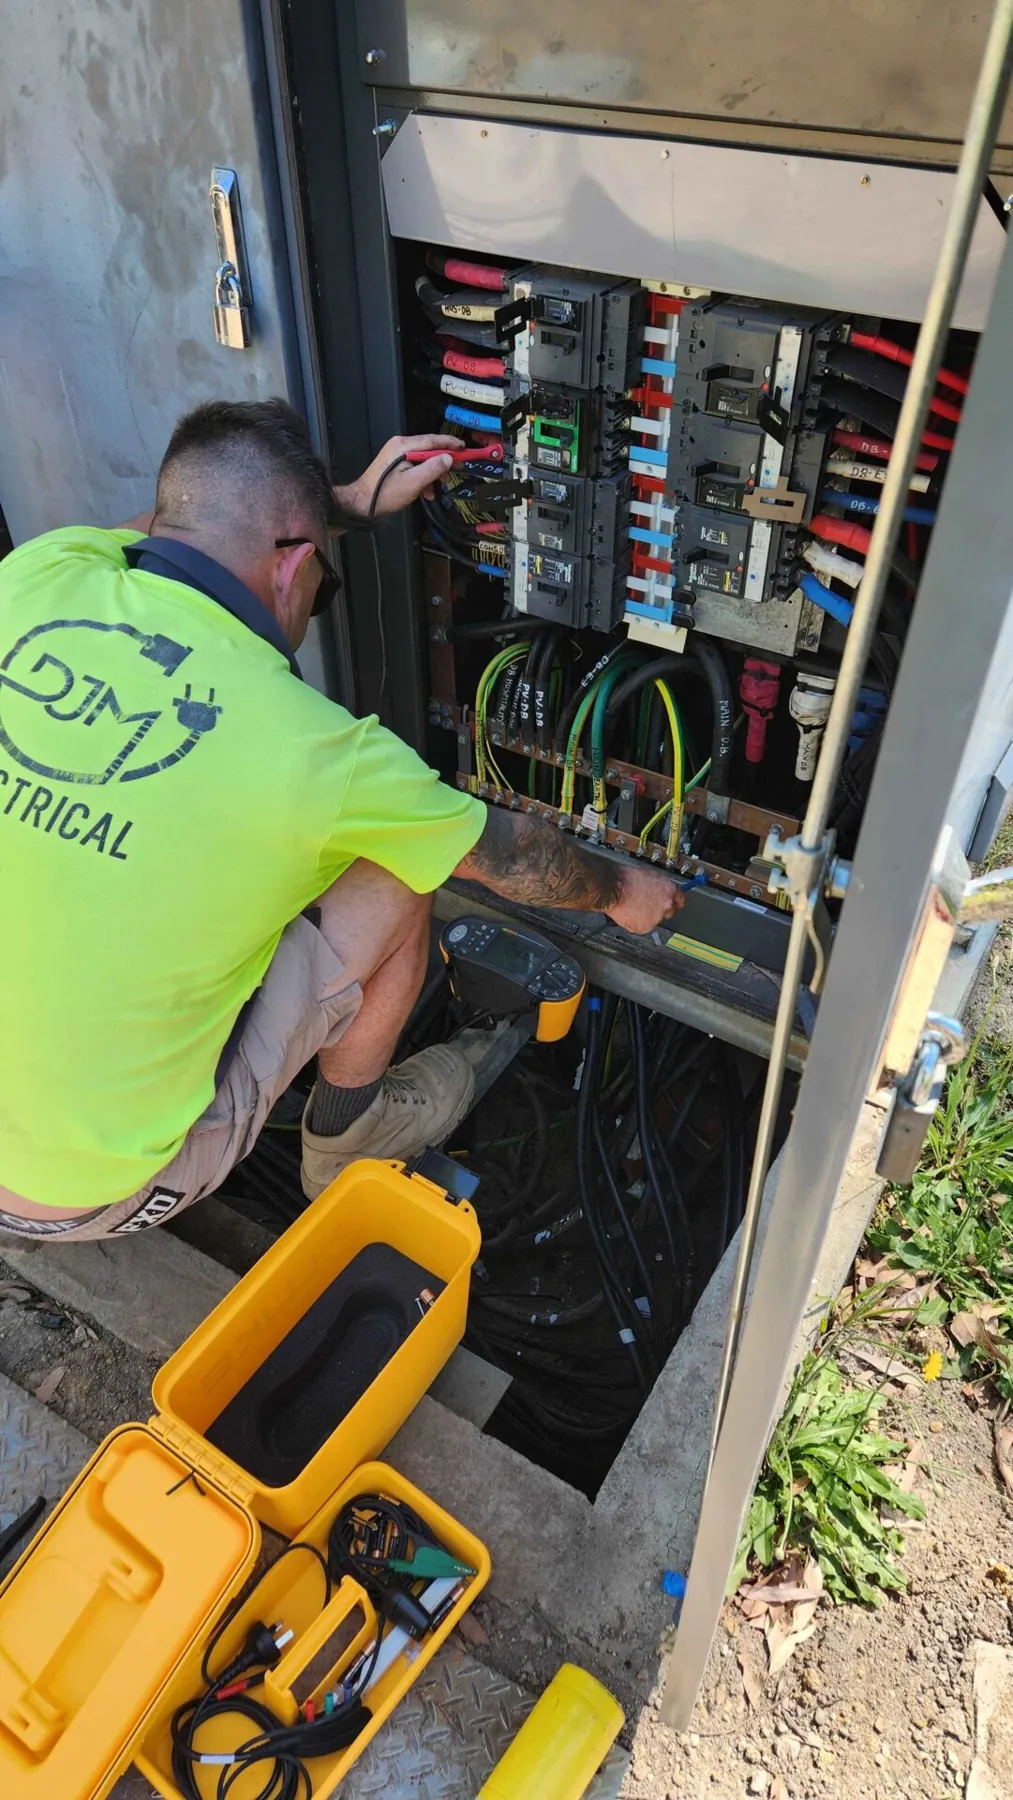
Dak checks your solar, your board, your usage and your eligibility for both schemes, in one visit.
Battery options sized to your evening load, with the federal discount taken off and the warranties listed.
If you want the zero-interest loan, you apply with the lender for the amount left on the quote. We tell you exactly what that is.
Installed by our crew, commissioned, monitoring on your phone, discount paperwork lodged by us.
Straight from Google
Live reviews from our Google Business Profile, rated 5.0. Read them before you ring us.
Good to know
Yes. The federal discount comes off the price first, and the zero-interest loan can cover what is left, up to $15,000. That is the order we quote it in.
Most homes and small businesses with solar, or installing solar at the same time, are. It is not means-tested. The battery has to be on the approved product list and installed by an accredited installer. We confirm your position at the assessment rather than guess.
It depends on the usable capacity of the battery and the date it is installed. The full rate covers the first 14 kWh, with a lower rate above that, and the rate steps down every six months. We show your exact figure on the quote, because a number printed here would be out of date by the next step-down.
NSW homeowners and landlords with a combined household taxable income of $210,000 or less, who pass the lender's credit check. Social housing and short-stay properties are excluded. Renters cannot take the loan themselves.
The NSW Government delivers Home Energy Saver loans through Brighte and Plenti. You apply with the lender, and you need the itemised quote with the federal discount already applied, which is what we give you.
NSW has also announced Home Energy Saver discounts of up to $4,000 for households earning up to $80,000 a year or holding an eligible concession card. If you qualify, the Government recommends claiming the discount before applying for the loan, and we factor it in.
No. To qualify for either program the battery has to be capable of joining one, but whether you actually sign up is your choice. Your battery runs your house first either way, and we will explain the trade-off honestly if you ask.
You can, but the discount drops again on 1 January 2027 and every six months after that. Waiting costs money in this case, which is unusual for us to say.
Related services
Where we work
Obligation-free quotes
Tell us what solar you have and the suburb. Dak checks your eligibility for the discount and the loan at the visit, and the numbers go on the quote.